

Real estate · Rent versus the payment
DSCR Loan Calculator
Short answer
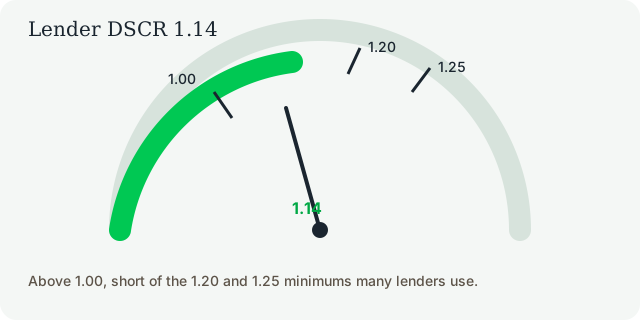
This sizes a DSCR loan for anyone whose lender is looking at rent, not a W-2. A $300,000 rental with 25% down and $2,500 rent shows a 1.14 DSCR to a typical lender and about $310 a month of rent left after PITIA. After vacancy, management, repairs, and CapEx the same deal loses $265.08 a month. It passes a 1.00 minimum and fails 1.20 and 1.25. The catch is that a passing lender ratio can still ask you for a check.
Last reviewed: November 18, 2026. Rates checked against the NPLA October 2026 market report, the Harpoon Capital DSCR index, and Freddie Mac PMMS. Illustration, not a forecast.
DSCR loan calculator
Type the price, the rate, and the rent. You get the lender DSCR, the max loan at your minimum, the rent that minimum needs, and the cash flow after real expenses. Educational only. Not financial advice.
DSCR ladder
| DSCR | Max PITIA | Max P&I | Max loan | LTV | Cash down | Rent needed now |
|---|
DSCR loan vs conventional loan
| DSCR loan | Conventional investor |
|---|
Prepay figure uses the balance at the end of the hold year.
| DSCR loan | Conventional investor loan |
|---|---|
| Rent and the property file | Personal income documents and DTI |
| Often closes in an LLC | Often a cap around 10 financed properties |
| Prepay penalty is common | Prepay penalty is less common |
| Higher rate and points in this example | Lower payment if you qualify |
How to use this calculator
- Type the price, the down payment, the rate, and the term. The example is a $300,000 house with 25% down, so the loan starts at $225,000.
- Add the rent, the tax, the insurance, and any HOA. HOA is part of PITIA here. The example HOA is $0, and a real bill makes the gross ratio worse.
- Read the lender DSCR first. That is the gross method this page leads with: monthly rent divided by PITIA. On the example it is 1.14.
- Then look at the NOI DSCR beside it. That one divides annual NOI by the year's principal and interest. On the example it is 0.85, and cash flow is -$265.08 a month.
- Leave the target at 1.25, or change it if your lender uses another minimum. You get the max loan at that target, plus the rent that would make this loan a 1.00 or a 1.25 on the gross method.
What the numbers mean
- Lender DSCR (gross, the hero)
- Monthly rent divided by PITIA. PITIA is principal, interest, taxes, insurance, and HOA. The example is 1.14. Many 1 to 4 unit DSCR lenders start here, and they leave your repairs out on purpose.
- NOI DSCR
- Annual NOI divided by annual principal and interest. NOI already takes out vacancy, management, repairs, CapEx, taxes, insurance, and HOA. The example is 0.85. Commercial sheets often look more like this.
- Max loan at the target
- The biggest loan whose PITIA is rent divided by the target. The target starts at 1.25, which supports $200,838.84 at $2,500 rent. The link leaves tdscr off while it stays 1.25.
- Rent for 1.00 and 1.25
- The rent that would put the gross DSCR on the current loan at those marks. That is $2,190.08 and $2,737.59 in the example. These follow the hero method, not the NOI method.
- True monthly cash flow
- NOI for the month minus principal and interest. The example is -$265.08. A lender can say yes while you still write that check.
Worked example: $300,000 rental at $2,500 rent
Price $300,000, 25% down, loan $225,000. DSCR rate 8.75% for 30 years. Tax $300 a month, insurance $120, HOA $0. Rent $2,500. Points 1.5% on the DSCR loan and 0.5% on the conventional loan at 8.18%. Illustration, not a forecast.
| Item | Value |
|---|---|
| P&I / PITIA | $1,770.08 / $2,190.08 |
| Lender DSCR | 1.14 (passes 1.00, fails 1.20 and 1.25) |
| Rent minus PITIA | $309.92 |
| Investor NOI / NOI DSCR | $18,060 a year / 0.85 |
| True monthly cash flow | -$265.08 |
| Max loan at 1.00 / 1.20 / 1.25 | $264,395.44 / $211,431.61 / $200,838.84 |
| Rent needed at 1.00 / 1.20 / 1.25 | $2,190.08 / $2,628.09 / $2,737.59 |
| 5-year extra cost vs conventional | $8,741.38 (interest plus points) |
| Prepay at the end of year 5 (5-4-3-2-1) | $2,153.00 |
The lender sees a 1.14 DSCR and $309.92 of rent left after the full house payment. That is the financing view. It ignores vacancy and repairs on purpose. After 5% vacancy, 8% management, 5% repairs, and 5% CapEx, NOI is $18,060 a year, the NOI DSCR is 0.85, and you write a check for $265.08 a month.
Interest-only changes the lender picture and not the equity. The IO payment is $1,640.62, PITIA is $2,060.62, and the lender DSCR rises to 1.21. The balance does not fall. Use IO to qualify only if you have a real plan for the principal later.
How DSCR lenders calculate the ratio
Most DSCR lenders divide gross rent by PITIA. They do not subtract vacancy, management, repairs, or CapEx. That is why a 1.14 can still lose money. Some lenders use a net rent figure instead. Ask which one is on your term sheet, then run both here.
For a vacant property the rent is usually the appraiser's market rent (form 1007), not the rent you hope to get. If the lease is lower than market, many lenders use the lower number. The DSCR loan calculator above uses the rent you type. If that rent is a wish, the ratio is a wish too.
The two formulas, with a plain-language walkthrough, are on what DSCR means and the two formulas. This page is the loan-sizing tool. That page is the definition.
DSCR loan rates in November 2026
There's no official national average for DSCR loans the way Freddie Mac publishes one for regular mortgages, so it helps to look at a few sources together. In mid-November 2026, a borrower with strong credit and 25% down was seeing roughly 7.25% to 7.5%, and the typical deal across private lenders priced near 7.75% with one point up front. Weaker credit or 80% leverage pushes it past 8%.
| Source and date | Scenario | Rate |
|---|---|---|
| NPLA market report, October 2026 | Median DSCR loan among member lenders (median fee 1 point) | 7.75% |
| Harpoon Capital DSCR index, Nov 18, 2026 | 760 FICO, 75% LTV, 1.25x DSCR, 5-year prepay | 7.44% |
| Harpoon Capital grid, priced Nov 5, 2026 | 680 to 699 FICO, 80% LTV | 8.33% |
| Harpoon Capital grid, priced Nov 5, 2026 | 660 to 679 FICO, 75% LTV | 8.25% |
| Freddie Mac PMMS, Nov 12, 2026 | Conventional 30-year, owner-occupied, 20% down (not a DSCR loan) | 7.11% |
The 8.75% default on this page is on purpose: it's what a borrower with middling credit and high leverage might be quoted, and it's better to be pleasantly surprised. Type 7.44% instead and the example changes a lot. The payment on $225,000 drops to $1,564.00, the lender DSCR climbs from 1.14 to 1.26, and the real cash flow after every expense improves from -$265.08 to about -$59 a month. Still negative. A better rate makes a thin deal less bad; it rarely makes it good.
NPLA also reported that 92.8% of DSCR loans in October priced at 7% or higher, and more lenders were reporting weaker investor demand. Shop at least three lenders and compare the rate, the points, and the prepay schedule together, since a lower rate with a 5% flat penalty can cost more than it saves.
Sources: National Mortgage Professional on the NPLA report, Harpoon Capital DSCR rate index, Freddie Mac PMMS.
How much DSCR loan can I get?
The max loan is the loan whose PITIA is rent divided by the minimum. At $2,500 rent and a 1.20 minimum, max PITIA is $2,083.33, max principal and interest is $1,663.33, and the loan is $211,431.61 (70.5% LTV). You would need $88,568.39 down on a $300,000 price, not the $75,000 a 25% down payment suggests.
A looser 1.00 minimum supports $264,395.44 (88.1% LTV) and $35,604.56 down. A 1.25 minimum supports $200,838.84 (66.9% LTV) and $99,161.16 down. Higher minimum, more cash at the table. If rent cannot cover taxes, insurance, and HOA at that ratio, the calculator says so instead of inventing a loan.
DSCR loan vs conventional loan
Same $225,000, different rate. Conventional at 8.18% is $1,679.29. The DSCR loan at 8.75% is $1,770.08, which is $90.79 more every month. Points are $3,375.00 versus $1,125.00. Interest over 5 years is $96,504.64 versus $90,013.25. Add the points and the DSCR loan costs $8,741.38 more across those five years.
You pay that premium for what the conventional loan will not do: close without your W-2, close in an LLC, or keep going after you already have a stack of financed properties. If you qualify for conventional and you plan to hold the property in your own name, the cheaper loan is usually the better loan. Self-employed borrowers, entity title, and speed are the cases where the extra $90.79 can be the rational price.
Points, prepayment penalties, and interest-only
Points buy the rate down or pay the lender. They are due at closing, so a lower rate that costs 1.5 points is not free. On $225,000, 1.5 points is $3,375.00. Compare that cash to the monthly savings and to how long you will actually keep the loan.
Prepay penalties are common on DSCR loans. A 5-4-3-2-1 step-down charges 5% of the balance in year 1, then 4%, 3%, 2%, and 1%, and nothing after year 5. On this loan the year-5 penalty is $2,153.00. Selling or refinancing in year 1 costs about $11,169.14. A 5% flat penalty does not step down. Interest-only raises the lender DSCR (1.21 here) and builds no equity. Cash-out loans often have seasoning rules and lower LTV caps. None of that is a promise that a specific lender will offer these terms.
When a DSCR loan makes sense for cash flow
It makes sense when the property still cash flows after the higher rate, the points, and a full expense load, and when conventional financing is a bad fit. Self-employed income that a conventional underwriter will not count, a purchase in an LLC, or a portfolio already past a conventional property cap are the usual reasons. Speed can matter on a competitive offer. A DSCR loan calculator is how you see the premium before you pay the points. It is still a loan, not a strategy.
It does not make sense on the default example. The lender ratio looks acceptable at 1.14 and the deal loses $265.08 a month once real costs are in. Read negative cash flow on a rental before you call that a short-term hold, and run a rental stress test with a lower rent. If the deal only works on the lender's gross-rent math, it does not work.
Frequently asked questions
What DSCR do I need for a DSCR loan?
Many lenders want 1.00 to 1.25 on gross rent divided by PITIA. In the default $300,000 example the lender DSCR is 1.14, so it clears a 1.00 minimum and misses 1.20 and 1.25. A higher minimum means a smaller loan: $264,395.44 at 1.00, $211,431.61 at 1.20, and $200,838.84 at 1.25. Ask the lender which formula they use. This is an illustration, not an approval.
How is DSCR calculated for a loan?
The common lender version is gross monthly rent divided by PITIA (principal, interest, taxes, insurance, and HOA). Here that is $2,500 / $2,190.08 = 1.14. The investor version uses NOI after vacancy, management, repairs, and CapEx, divided by principal and interest. That NOI DSCR is 0.85 on the same deal. Both numbers are useful. They answer different questions. See what DSCR means and the two formulas.
Can I get a DSCR loan with a ratio under 1?
Some lenders allow it, often with a lower LTV, a higher rate, or extra reserves. A ratio under 1.00 means rent does not cover PITIA, so you are feeding the payment from day one. In this example the lender ratio is 1.14, but the true cash flow is still -$265.08 a month. Passing the lender test is not the same as getting paid.
Are DSCR loan rates higher?
Usually yes. In mid-November 2026 the Harpoon Capital DSCR index was 7.44% for a 760 FICO, 75% LTV borrower, and NPLA put the October median at 7.75%, against a 7.11% Freddie Mac average for conventional owner-occupied loans (November 12). The example here is deliberately conservative: 8.75% for the DSCR loan and 8.18% for a conventional investor loan (the November 5 Freddie Mac average of 7.18% plus 1 point). On a $225,000 loan that is $1,770.08 versus $1,679.29, or $90.79 more a month. Over 5 years the interest-plus-points gap is $8,741.38. Example rates, not offers. Lenders price on credit, LTV, DSCR, and the prepay term.
Do DSCR loans have prepayment penalties?
Often, yes. A 5-4-3-2-1 schedule on this loan is about $11,169.14 if you sell or refinance at the end of year 1, $8,864.73 at the end of year 2, $6,590.79 at the end of year 3, and $2,153.00 at the end of year 5. A flat 5% penalty is harsher. Put the schedule from your term sheet into the calculator. Do not guess.
Is a 1.25 DSCR good cash flow?
Not by itself. A 1.25 lender DSCR on this loan needs $2,737.59 of rent, and the max loan at 1.25 with $2,500 rent is $200,838.84. The investor view can still be thin once vacancy, management, repairs, and CapEx come out. On the default inputs the NOI DSCR is 0.85 and cash flow is -$265.08. Read 1.25 as a financing test, then run the full expenses.
Which DSCR does this page lead with?
The hero number is the gross method many 1 to 4 unit lenders use: monthly rent divided by PITIA (principal, interest, taxes, insurance, and HOA). On the default deal that is $2,500 / $2,190.08 = 1.14. The NOI method is shown beside it: annual NOI divided by annual principal and interest, which is 0.85 here. Passing the gross test is not the same as cash flow.
How does the target DSCR change the max loan?
The target starts at 1.25 and stays out of the share link until you change it. The max loan is the loan whose PITIA equals rent divided by that target. At 1.25 with $2,500 rent the max loan is $200,838.84. Rent that would make the current loan a 1.00 gross DSCR is $2,190.08. Rent for 1.25 is $2,737.59. Both rent figures use the gross method, which is the hero on this page.
More free loan and debt tools: 15 vs 30 year mortgage, HELOC, debt snowball, rent vs buy, cash-out refinance. See the full loans and debt list.
Educational only. Not financial advice. Lenders set their own DSCR formulas, minimums, rates, and terms, and a 1.14 on this page is not an approval. Example rates, not offers.