

Real estate · Cash or a loan inside the Roth
Roth IRA Real Estate Calculator
Short answer
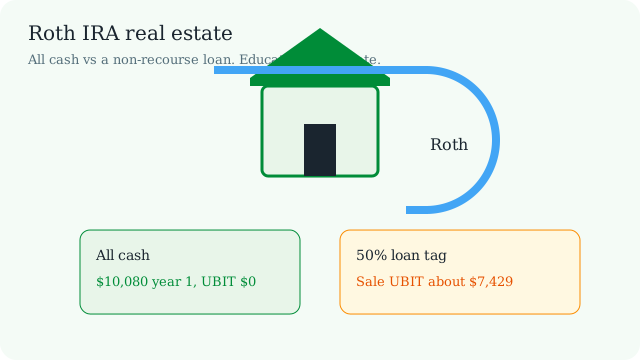
Paying cash inside a Roth, this $150,000 rental throws off about $10,080 a year with no UBIT, and no tax on the sale in this sketch if withdrawals are qualified. A 50% non-recourse loan at 9.5% drops cash-on-cash to 2.84%, and about $7,429 of UBIT shows up at sale. This Roth IRA real estate calculator is for someone comparing cash with a loan inside the account. The caveat: UBIT and the custodian rules are not optional, and this sketch is not a tax return.
Last reviewed: November 2026. Talk to a tax pro and your custodian first.
Roth IRA real estate calculator
This Roth IRA real estate calculator compares the same rental inside a self-directed Roth and in your own name. The all-cash case needs $153,000 and produces $10,080 of year-1 NOI. UBIT on that case is $0. Add a loan and the debt-financed fraction can create tax the IRA has to pay. Educational only. Not tax, legal, or financial advice.
How to use this calculator
- Leave the loan percent at 0. The example year-1 cash flow is $10,080 and simple UDFI is $0.
- Move the loan percent to sketch a non-recourse note. Cash flow follows the payment.
- Read simple UDFI beside cash flow. It is loan divided by price, times net taxable rental income. It is not inside the old cash flow total.
- Read the prohibited-transaction list. This is a warning list, not legal advice.
- Compare a solo 401(k) only as a note: it is not subject to UDFI on leveraged real estate the way an IRA is. No promise.
- Copy the link if you want these inputs again. Check with a tax pro.
Worked example: a $150,000 rental, all cash vs 50% loan
The worked example in this Roth IRA real estate calculator is a $150,000 price, $3,000 of closing, $1,400 rent growing at 3%, operating costs at 40% of rent, land at 20%, a 10-year hold, and 3% appreciation. All cash, the IRA puts in $153,000. There is no payment. Year-1 NOI and cash flow are both $10,080. Cash-on-cash is 6.59%. Depreciation is $4,450.91 a year. The debt-financed fraction is 0. UDFI is $0. UBIT is $0.
Over 10 years the all-cash cash flow adds to $115,555.90. The same deal in a personal name at a 24% bracket owes about $17,051.24 of income tax on the positive net. At sale the value is $201,587.46, adjusted basis is $108,490.91, and gain is $93,096.55. The simplified personal sale tax is about $18,415.39. Inside the Roth, all cash, the sale tax in this model is $0. Equity is the whole $201,587.46. The Roth IRA real estate calculator keeps those two sale lines side by side.
The 50% case borrows $75,000 at 9.5% for 25 years. The payment is $655.27 a month. Cash in is $78,000. Year-1 cash flow is $2,216.73 and cash-on-cash is 2.84%. Interest in year 1 is $7,091.99. The debt-financed fraction is 49.49%. UDFI is still $0 in year 1 because the net after interest and depreciation is under the $1,000 deduction, so year-1 UBIT is $0. Across 10 years, operating UBIT is about $71.27 and personal income tax on the same loan is about $1,961.34. Equity at year 10 is $138,835.40. The debt-financed share at sale is 48.00%, and UBIT on that sale is about $7,428.95. Beside that, the simple teaching line is loan divided by price, 50%, times the year-1 net of about -$1,462.90, which is about -$731.45. That illustration is not inside the $2,216.73 of cash flow. Check with a tax pro.
How buying real estate in a Roth IRA works
A normal brokerage Roth holds funds and stocks. A self-directed Roth can, if the custodian allows it, hold a rental. The IRA is the owner on the deed and the account that pays the bills. You do not write a personal check for the roof and then invoice the IRA later. Contribution limits are small next to a house, so most people who do this roll over or convert money that is already in an IRA. That rollover is its own tax decision. The Roth IRA real estate calculator does not model the rollover.
The Roth IRA real estate calculator then runs a simple year. Rent grows. Operating costs stay a flat percent of that rent. The loan, if any, amortizes monthly. Depreciation is straight-line on the building for a full year, which is rougher than the mid-month rule a personal return uses. Cash flow is NOI minus the payments. It stays in the IRA. You cannot spend it on groceries until a qualified withdrawal.
The rules that trip people up
Plain-language rules. Prohibited transactions and disqualified persons include you, a spouse, parents, children, and their spouses. No personal guarantee: the note should be non-recourse. No sweat equity: do not paint it yourself. All income stays in the IRA, and expenses are paid from the IRA. A self-directed custodian is required. Contribution limits mean most people roll over or convert an existing balance. One mistake can disqualify the whole IRA. Talk to a tax pro and your custodian first.
Prohibited transactions
- Do not buy from or sell to yourself or a disqualified person.
- Do not live in the property.
- Do not personally fix it (sweat equity).
- Do not use the property as collateral for a loan you personally guarantee.
This is a warning list, not legal advice.
The checklist on the Roth IRA real estate calculator is a list of those ideas with pass, watch, or fail text. A checked box is you saying the statement is true. The page cannot see the operating agreement, the note, or who fixed the faucet. Reserves pass when the cash you typed covers about six months of operating costs plus the payment. Short of that, and above zero, the line says watch.
UBIT and debt-financed income in plain English
A Roth does not make debt-financed rent invisible. UDFI is the debt-financed slice of income. This model sets the fraction to average debt that year divided by average adjusted basis (basis minus depreciation through the middle of the year), and caps it at 100%. UDFI is that fraction times NOI minus interest minus depreciation, then minus $1,000, and never below zero. UBIT is the 2026 trust ordinary tax on that UDFI: 10% to $3,300, 24% to $11,700, 35% to $16,000, and 37% above. A check in the engine: $5,000 of UDFI is $738 of tax, and $20,000 is $5,331.
At sale, the debt-financed share is the loan balance divided by the average of original basis and adjusted basis. The Roth tax uses trust long-term gain rates on gain times that share, minus $1,000: 0% to $3,300, 15% to $16,250, and 20% above. Those bands live in the script as TRUST_2026, from IRS 2026 Form 1041-ES and Rev. Proc. 2025-32. The Roth IRA real estate calculator labels every one of these lines as an estimate. A real Form 990-T is a different document.
There is also a simple teaching line next to the result. Debt-financed fraction equals the loan divided by the purchase price. UDFI on that line equals net taxable rental income (NOI minus interest minus depreciation) times that fraction. Tax is not recomputed as a second bracket. On the 50% example the net is about -$1,462.90, the fraction is 0.50, and simple UDFI is about -$731.45. Year-1 cash flow stays $2,216.73. When the loan is $0, simple UDFI is $0 and the all-cash cash flow stays $10,080. Check with a tax pro. Real UDFI uses average acquisition indebtedness over average basis, which this illustration simplifies.
A solo 401(k), in one paragraph
A solo 401(k) is not subject to UDFI on leveraged real estate the way an IRA is. That is a difference in the debt-financed income rule, not a promise that a solo 401(k) is available to you, that a custodian will allow the purchase, or that the cash flow will be better. This page does not estimate contribution room. Check with a tax pro before you pick an account.
Roth IRA vs owning it yourself
Depreciation is useful in a personal name because it can shelter rent from income tax. Inside a Roth, that shelter often has nothing to shelter, unless a loan creates UDFI. Open the Roth IRA real estate calculator and read the personal column next to the Roth column. The all-cash personal owner in the example still pays tax on the net, about $17,051.24 over 10 years at 24%, and a simplified sale tax of about $18,415.39. The sale sketch is depreciation taken times 25%, plus the gain above original basis times 15%. No selling costs. No state tax. The Roth all-cash column is $0 and $0 on those two lines in this model.
Leverage flips the story. The payment eats cash flow, cash-on-cash falls from 6.59% to 2.84%, and the sale picks up about $7,428.95 of UBIT while the personal sale tax on the same building stays about $18,415.39. Lower tax is not the same as a better deal. The IRA also gave up the right to use the cash along the way. Read both columns on the Roth IRA real estate calculator before treating the Roth as a free lunch.
Cash flow you cannot spend (yet)
$10,080 a year inside the account is not $10,080 in your checking account. A qualified withdrawal needs age 59 and a half and the 5-year clock. Until then the cash flow can pay the next repair, sit as reserves, or buy another asset the custodian allows. It does not replace a paycheck this month. Use the retirement calculator for the age and savings picture, and the financial freedom calculator for cash flow you can actually spend.
If the plan is a rental in your own name, with a normal loan and a normal tax return, this Roth IRA real estate calculator is the wrong desk. The depreciation and cash-flow tools on the real estate hub match that job. Come back here only when the owner on the deed would be the IRA.
What the numbers mean
- Year-1 cash flow
- NOI minus the loan payments. At the default loan percent of 0, this is $10,080. It does not change when the simple UDFI line is $0.
- Loan / purchase
- The simple debt-financed fraction. A 50% loan on the $150,000 example is 0.50. The other fraction on the year table is average debt divided by average adjusted basis.
- Simple UDFI
- NOI minus interest minus depreciation, times the simple fraction. About -$731.45 at 50% loan in year 1, and $0 when the loan is $0. Shown beside cash flow, not inside it.
- UBIT
- Trust tax on the average-basis model. All cash is $0. The 50% example is about $71.27 over 10 years of operations, plus about $7,428.95 at sale. Check with a tax pro.
Frequently asked questions
Can I buy rental property with a Roth IRA?
Some self-directed custodians allow it. The Roth IRA real estate calculator shows the cash and the tax sketch. It does not say a custodian will accept the deal. On the example, all cash needs $153,000 and year-1 cash flow is $10,080. That cash stays in the IRA. Talk to the custodian and a tax pro before you move money.
What is UBIT on IRA real estate?
UBIT is unrelated business income tax. For a rental, the piece that matters here is UDFI: debt-financed income. This Roth IRA real estate calculator taxes the average-basis piece with 2026 trust brackets after a $1,000 deduction. All cash has a debt-financed fraction of 0 and UBIT of $0. A 50% loan at 9.5% still has $0 of UDFI in year 1 on that model because the net is under the deduction, then about $71.27 of UBIT over 10 years and about $7,428.95 at sale. A simpler teaching line sets the fraction to loan divided by purchase price and multiplies year-1 net taxable rental income by that fraction. At 50% that illustration is about -$731.45 and it sits beside cash flow. It is not subtracted from the $2,216.73. When the loan is $0, that UDFI is $0. Check with a tax pro. Real UDFI uses average acquisition indebtedness over average basis, which the simple line simplifies.
Can I get a mortgage inside a Roth IRA?
A personal guarantee is not the path this page models. The loan in the Roth IRA real estate calculator is non-recourse: the lender looks to the property, not to you. The example 50% loan is $75,000 at 9.5% for 25 years, about $655.27 a month. Cash in falls to $78,000. Year-1 cash flow falls to $2,216.73 and cash-on-cash to 2.84%. The 9.5% rate is an example, not a quote. Do not use the property as collateral for a loan you personally guarantee.
Can I manage my IRA rental myself?
The safe reading of the rules is no. You, a spouse, parents, children, and their spouses are disqualified persons. Do not buy from or sell to yourself or a disqualified person. Do not live in the property. Do not personally fix it. Hire the work and pay it from the IRA. The warning list on this page is not legal advice. Ticks are reminders, not a legal opinion.
Is rental income in a Roth IRA tax-free?
All-cash rental income inside a Roth is not hit by this UBIT sketch, and a qualified withdrawal (age 59 and a half, plus the 5-year rule) is the tax-free part people mean. It is not automatic. The same building held personally owes about $17,051.24 of income tax over 10 years at a 24% bracket, and about $18,415.39 of simplified tax at sale. Inside the Roth, all cash, those two lines are $0 in this model. A loan can put tax back on the debt-financed share. A solo 401(k) is not subject to UDFI on leveraged real estate the way an IRA is. That is not a promise that a solo 401(k) fits you.
What happens if I break the rules?
A prohibited transaction can disqualify the whole IRA, not just the rental. The tax cost of that can dwarf the cash flow. This Roth IRA real estate calculator cannot detect a bad plan. One mistake is enough to talk to a tax pro and the custodian before the purchase, not after. This is a warning list, not legal advice.
Educational only. Not tax, legal, or financial advice. Self-directed IRA rules are strict and mistakes can be costly. UBIT figures are simplified estimates using 2026 trust rates.